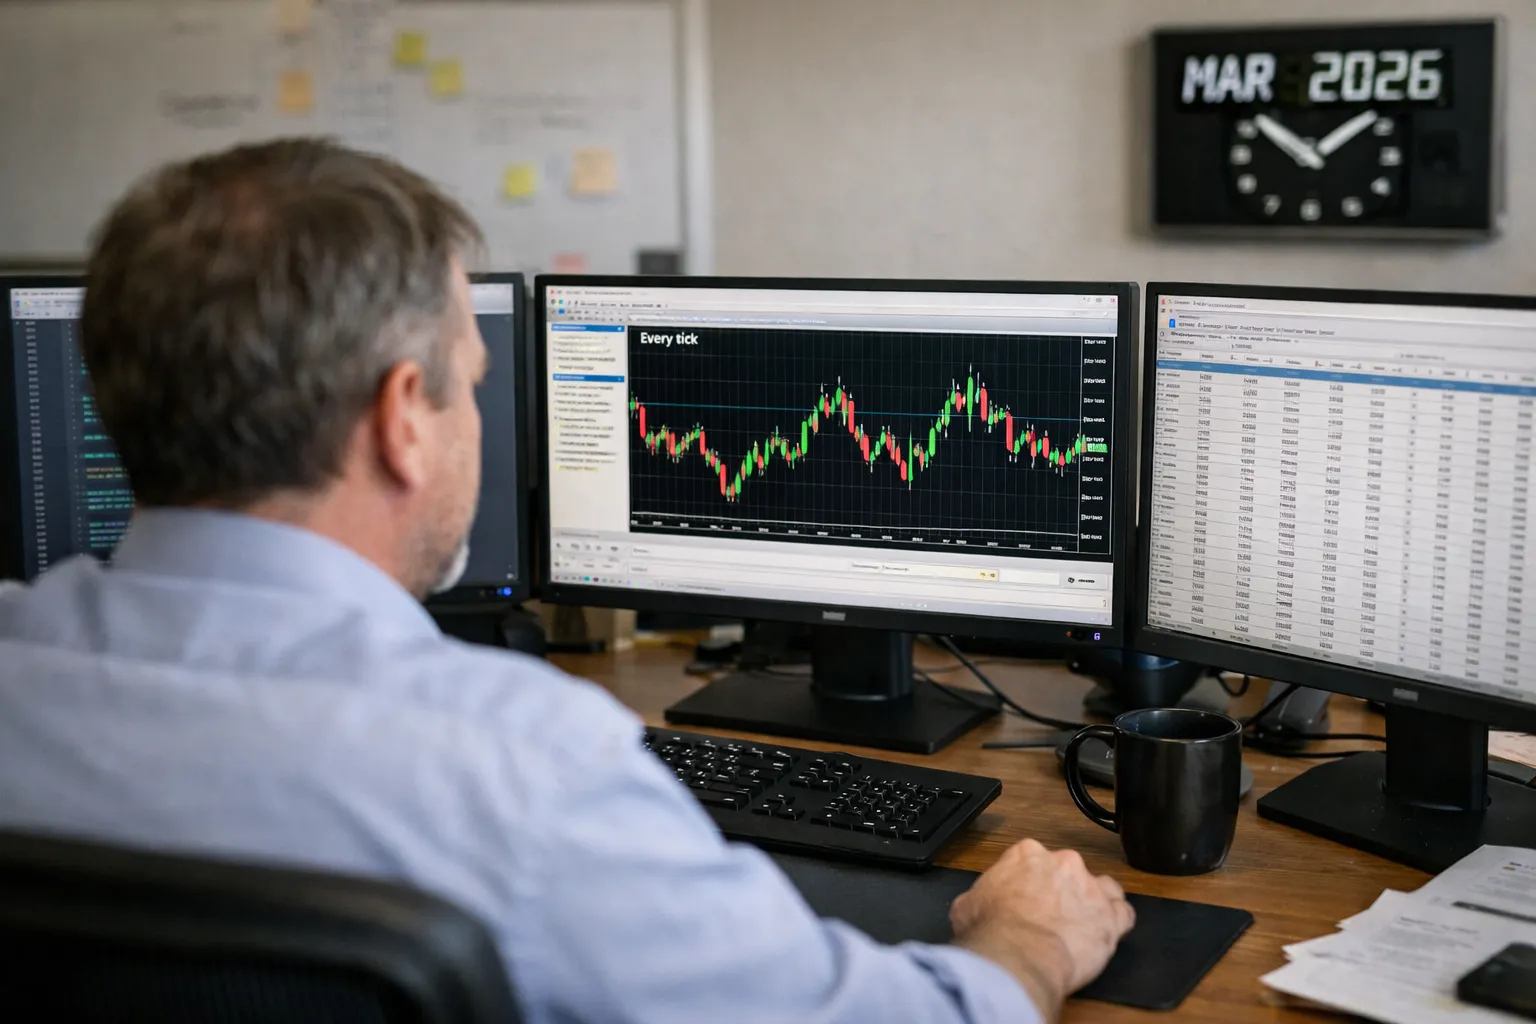
MetaTrader 5’s Strategy Tester remains the first stop for many retail and semi‑professional FX algo developers. This June 2026 update re‑examines the tester’s capabilities, highlights recent trends and tooling that change how traders validate systems, and gives practical, immediately actionable advice for using MT5 as part of a modern validation pipeline.
Overview — What we’re reviewing
Product: MetaTrader 5 Strategy Tester (desktop). Key specs at a glance:
- Simulation modes: Every tick, 1‑minute OHLC, Open prices only.
- Optimization: Brute‑force and genetic algorithms; multicore local and MQL5 Cloud Network options.
- Integration: Runs native MQL5 EAs; has a Python API for data exchange and orchestration.
- Accessibility: Free desktop software; requires tick history to maximize fidelity.
Background — Who makes this and who it’s for
MetaQuotes Software develops MT5. The Strategy Tester targets retail algo traders and small prop shops that need a low‑cost, fast feedback loop between coding and backtests. It’s especially popular among developers writing MQL5 EAs, hobbyists experimenting with parameter sweeps, and traders validating medium‑frequency systems where market impact is low.
Features analysis — what's new and what still matters
Since the earlier March 2026 review, two practical shifts matter to MT5 users in June 2026:
- Broader availability of pre‑converted tick archives: More tick‑data vendors and community tools now offer MT5‑ready tick files (compressed .ticks/.hst) and sessionized spreads. That reduces friction when running Every‑tick tests with higher‑quality history.
- Wider use of hybrid testing workflows: Traders increasingly combine MT5’s tester with Python orchestration, cloud compute for large optimizations, and external post‑processing (Monte Carlo and walk‑forward frameworks) rather than relying solely on built‑in optimization reports.
Core strengths unchanged:
- Code parity: The tester runs the same MQL5 code used live, reducing “it worked in backtest, not in production” issues.
- Visual mode and forward testing: Visual replay and in‑tester forward slices remain useful for behavioral checks.
- Accessible optimization: Local multicore and MQL5 Cloud Network still accelerate parameter sweeps for modest dimensionality.
Practical limitations — updated context for June 2026
The tester remains powerful for logic validation, but the following limitations still materially affect strategy conclusions:
- No order‑book / market impact: MT5 does not simulate L2 depth or transient market impact. If your strategy trades size relative to displayed depth, results will be optimistic.
- Execution model variances: The platform provides simple slippage and deviation models, but these rarely match specific broker fill policies or ECN matching engines. Expect discrepancies between simulated and live slippage.
- Tick quality still decisive: Every‑tick mode’s fidelity is tied to the tick feed. Using native platform history remains insufficient for many intra‑day strategies; importing vendor or broker tick dumps is best practice.
- Spread and latency modeling: Static spreads still understate real costs. In 2026, more traders are using sessionized spread curves and injecting synthetic latency/disruption to expose fragility, but this is user‑implemented rather than native.
- Statistical robustness not native: There’s no packaged, statistically rigorous Monte Carlo/walk‑forward suite in MT5. Community scripts exist, but serious robustness analysis usually lives in external Python/R toolchains.
How I re‑tested — June 2026 methodology
To ground the update I re‑ran three representative experiments between April–May 2026 on a typical retail workstation and a small MQL5 Cloud node pool:
- EUR/USD scalper EA: every‑tick mode using a vendor‑supplied 2019–2026 tick archive with sessionized variable spreads.
- Swing mean‑reversion EA: 2016–2025 sample with walk‑forward partitions and stochastic slippage injection (randomized within broker‑reported ranges).
- Parameter optimization: 25‑parameter sweep using local multicore + MQL5 Cloud Network for an initial grid, exporting top parameter sets for external Monte Carlo and trade‑sequence perturbation in Python.
Key updated observations: the scalper’s edge was eliminated once sessionized spreads and randomized execution delays were applied — consistent with broader practitioner reports in 2025–26 that low‑latency retail scalps require venue access, not just code tweaks. The swing EA persisted under robust walk‑forward checks when tick quality and spread curves were realistic.
Workarounds and current best practices (June 2026)
To use MT5 effectively today, adopt these updated steps:
- Source MT5‑ready tick archives: Buy or obtain vendor‑converted MT5 tick files (many vendors now publish them). Use sessionized files that include bid/ask spread history.
- Model dynamic spreads and microstructure: Build or buy spread curves by session/volatility and inject them either via synthetic ticks or directly inside the EA.
- Randomize execution: Add randomized slippage and occasional partial fills to approximate broker behavior; capture broker fill stats on demos to calibrate the distribution.
- Use hybrid test pipelines: Run parameter sweeps and behavioral checks in MT5, then export trades to Python for Monte Carlo, walk‑forward automation, and statistical tests using libraries such as pandas, NumPy and custom walk‑forward toolkits.
- Demo and micro‑live validation: After backtest and simulated robustness checks, validate on broker demo and micro‑accounts to measure real-world fills and re‑calibrate execution models.
Pricing and value
MT5 desktop and its basic Strategy Tester are free. Costs you should budget for in 2026:
- High‑quality tick data: vendor fees typically range from ~$50–$500 depending on timeframe and currency pairs.
- VPS and cloud compute for large optimizations: small MQL5 Cloud tasks are inexpensive; full cloud sweeps on AWS/GCP for Python post‑processing typically run from $50–$500+ depending on scale.
- Third‑party tools (tick converters, spread models): many are one‑time purchases or subscriptions $50–$300 annually.
Overall: MT5 is low cost as a development sandbox, but a realistic validation pipeline requires modest additional investment in data and compute to get credible results.
Who it's for — updated June 2026 profile
MT5 Strategy Tester is best for:
- Retail developers validating MQL5 logic and mid‑frequency swing systems.
- Traders who want a fast local feedback loop and are prepared to invest in tick data and execution modeling.
- Hobbyists or small teams building prototypes before migrating to more scalable engines.
Not recommended as the sole validation tool for high‑frequency market‑making, size‑sensitive liquidity provision, or institutional desks requiring L2 book simulation and multi‑venue DMA analysis.
Alternatives
- QuantConnect (Lean): Cloud backtesting with multi‑asset support and easier integration of Python statistical tooling — good for scaling beyond MT5.
- Backtrader / custom Python stacks on cloud: More flexible for bespoke Monte Carlo, walk‑forward and event‑level execution modeling when paired with tick data.
- Professional market‑data simulators (OneTick, proprietary vendor suites): Provide order‑book replay and impact models needed for institutional workflows.
Verdict — June 2026
MT5 Strategy Tester remains a necessary and pragmatic tool for retail FX algo development in 2026. It excels at logic validation, quick optimization cycles and visual trade replay. However, it is rarely sufficient alone for robust performance claims: order‑book effects, dynamic spreads and realistic execution must be modeled externally. For most retail developers the optimal workflow is hybrid — MT5 for EA parity and rapid iteration, plus external tick data, Monte Carlo/walk‑forward tooling and demo/micro‑live validation to close the gap to real markets.
Final recommendation
Use MT5 as your development sandbox, but treat backtest PnL as directional. Invest in quality tick history, sessionized spread models, randomized execution, and an external statistical pipeline. Validate on demo and micro accounts before scaling. With those steps in 2026, MT5 is practical, cost‑efficient and still one of the best first tools for retail FX algo work.
Frequently asked questions
Do I need vendor tick data to trust Every‑tick mode?
Yes. Every‑tick mode is only as accurate as the tick feed. Native MT5 history often omits intra‑minute spread dynamics; vendor or broker tick archives with bid/ask timestamps significantly improve realism.
Can I simulate partial fills and order‑book impact inside MT5?
Not natively. You must approximate partial fills and impact in your EA (randomized partial reductions, execution delays) or use external simulators that replay L2 book snapshots for true impact modeling.
Is the MQL5 Cloud Network sufficient for large optimizations?
It's useful for medium‑scale sweeps and reduces local runtime. For very large parameter spaces or heavy Monte Carlo workloads, combine MQL5 Cloud with external cloud compute (AWS/GCP) and export results for Python‑based analysis.
How do I calibrate slippage models?
Collect live demo or micro‑account fill data (timestamps, sizes, reported slippage) and fit a distribution (e.g., empirical or parametric). Use that distribution to randomize slippage in backtests, and update it regularly.